Buying a home in Portugal? Get your mortgage structured by a licensed local specialist.
We help expats and international buyers secure financing from Portuguese banks. In English, fully remote, from the first numbers to the deed.
Mortgage broker licensed by Banco de Portugal
10
Partner banks in Portugal
Global Clients
Clients in the US, the UK, the Netherlands and beyond.
Check what you may borrow
Free initial analysis. We reply within one business day.
ALREADY LIVING IN PORTUGAL
Still paying rent?
In many cases the monthly instalment is close to, or even lower than, what you already pay in rent.
The difference at the end: the home is yours.
If you live and pay taxes here, you can apply for a mortgage on the same terms as Portuguese residents.
Partner banks in Portugal
WHY PORTUGAL
A euro asset, under EU law, in one of the most liveable countries in Europe.
A secure legal framework
Property is recorded in a public land registry and every sale is formalised by deed. Ownership is clear and verifiable before you sign.
A lifestyle that is hard to match
Climate, safety, food and a short flight from most European capitals. A home you will actually want to use.
Rental demand and new incentives
Long-term rental demand in many cities, and since 2026 new tax incentives for moderate-rent leases. Ask your tax adviser how they apply to you.
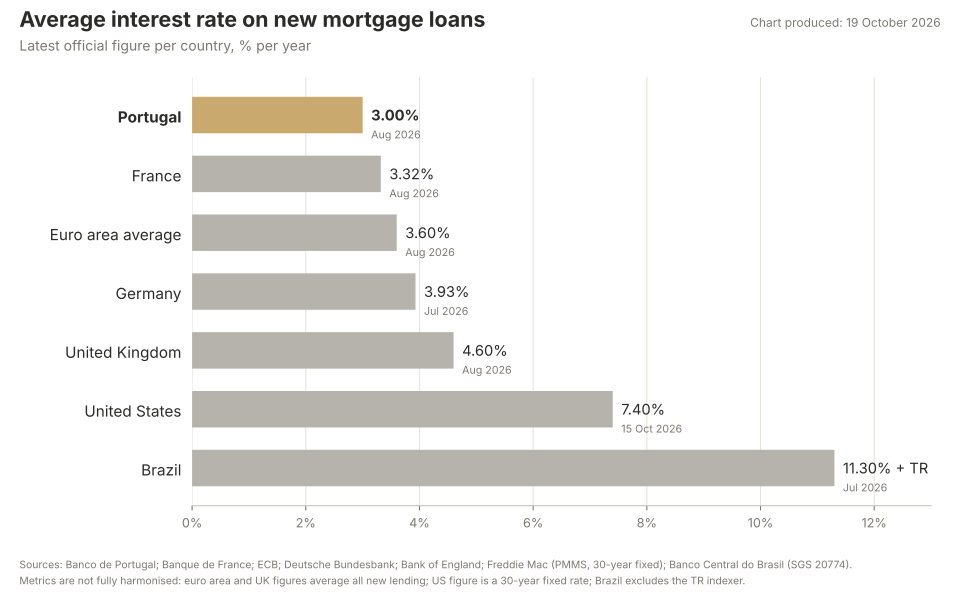
mortgage rates around the world
Among the lowest mortgage rates you will find
Portugal’s average rate on new home loans was around 3%, according to Banco de Portugal (August 2026), below the euro area average and well below the United States, the United Kingdom and Brazil. For a buyer financing a home over decades, that difference adds up to tens of thousands in interest.
ELIGIBILITY
Can foreigners get a mortgage in Portugal? Yes.
Each bank sets its own rules. These are the criteria that matter most.
Financing
Non-residents can typically finance up to 70% of the property value. Residents can go higher for a main home.
Affordability
Your total monthly debt payments, including car loans and credit cards, should generally stay under 45% of your net income. Banks also test whether you could afford a rise in rates.
Term
Up to 40 years if you are 35 or younger, and up to 35 years after that. Most banks also want the loan to end by around age 75.
Documents
ID, recent tax returns, proof of income, recent bank statements and a credit report from your country, translated where required.
HOW BUYING WORKS IN PORTUGAL
Four steps, usually 45 to 90 days.
01 Tax number and bank account
You need a Portuguese tax number (NIF) and a local bank account. Both can be arranged remotely. Buyers from outside the EU may need a tax representative, and we can point you to one.
02 Mortgage pre-approval
Before you commit to a property, we get your financing pre-approved. You negotiate knowing exactly what you can borrow.
03 Offer and promissory contract
Once the price is agreed, buyer and seller sign a promissory contract (CPCV), usually with a deposit. With pre-approval in hand, your deposit is far safer.
04 Final approval and deed
The bank values the property and issues its binding offer; by law you have at least 7 days to review it. Then the deed (escritura) is signed and the property is registered in your name. You can sign through a power of attorney.
Budget beyond the price
Transfer tax (IMT), stamp duty, notary, registry and bank fees are paid on top of the purchase price. Non-resident buyers pay a flat 7.5% IMT on residential property. It is a one-off cost; a lower interest rate is something you benefit from every month, for decades.
Planning to move to Portugal? The timing of your tax residency can change what you pay. Talk to us before you sign.
what we do
On your side of the table.
We are not a bank and not a real estate agency. We are a mortgage broker registered with Banco de Portugal, working with 10 partner banks. The banks pay our fee and our job is to find the financing that fits you best among them.
I. We compare offers from 10 partner banks
Not just the rate: spread, rate type, insurance, fees and the products each bank asks you to take in return.
II. We prepare and present your file
Foreign income, foreign tax returns, translations. Your application reaches the bank complete and credible.
III. One point of contact, in English
From the first analysis to the deed, the same team follows your process, wherever you are.
Tell us about your plans.
A first view of what you can borrow and what it will cost, within one business day. Free, with no commitment. Prefer to talk?
I also need information about insurance